
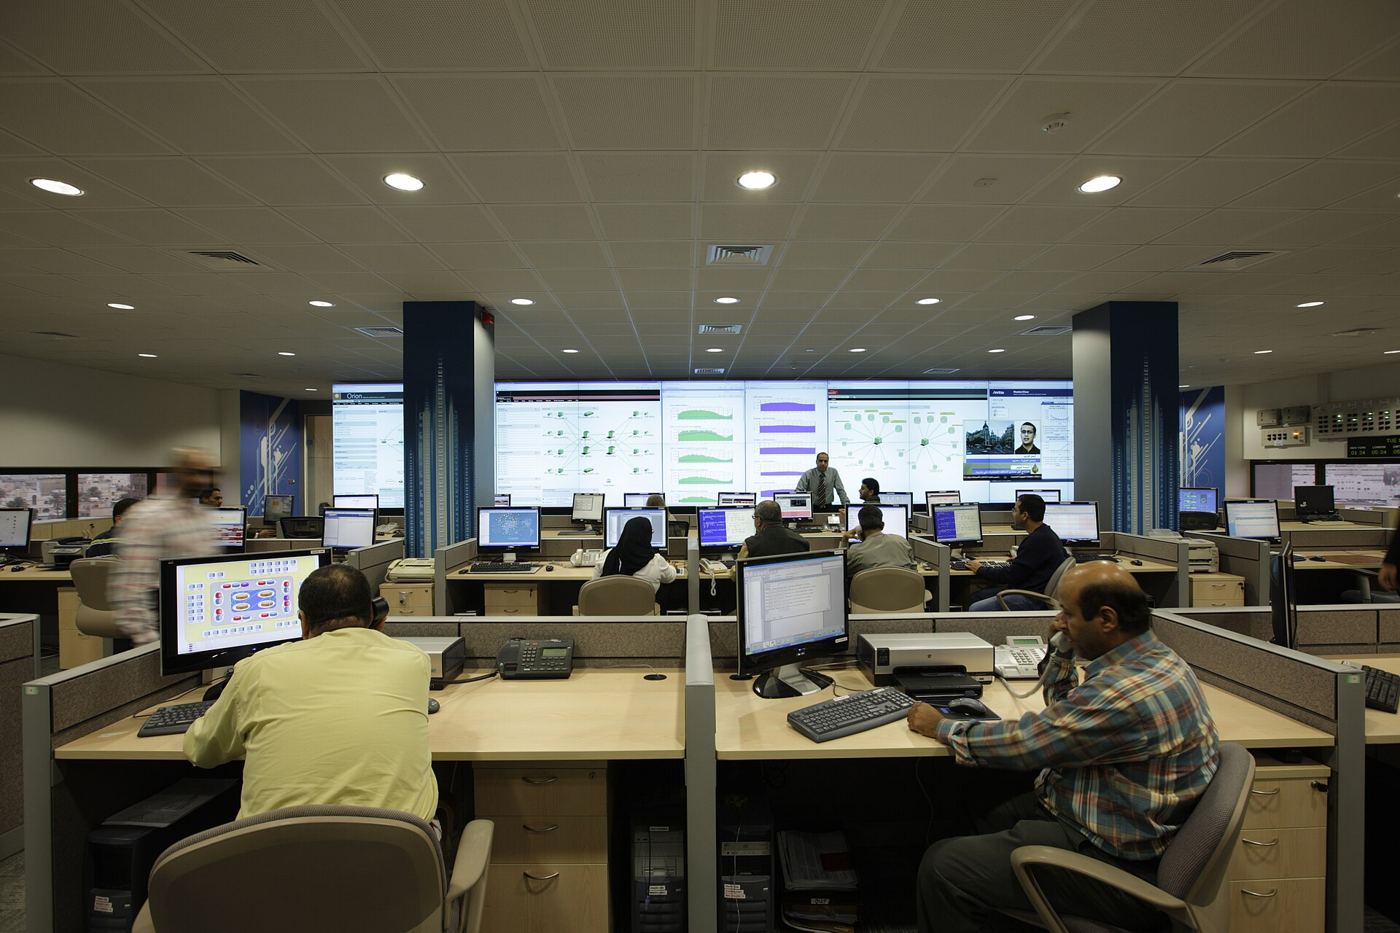
Banks are expanding their fraud monitoring teams as scam reports climb, hiring analysts and investing in systems that can spot suspicious payments in seconds rather than hours. Criminals have become adept at impersonating banks, delivery firms and government departments, and their messages now arrive by text, email, phone and social media, often tailored with personal details gathered from data breaches. In response, banks are combining human judgement with software that learns a customer’s normal patterns — the usual shops, typical amounts and regular times of day — and pauses anything that breaks the pattern for a check. Victims’ groups welcome the investment, while noting that prevention still depends on customers pausing before they act. A payment sent willingly to a fraudster is far harder to recover than a stolen card transaction, which is why banks are also spending more on warning messages at the moment of payment.
What the Evidence Shows
Industry figures show that reimbursement rules are also changing, with banks increasingly sharing the cost of authorised fraud when they could reasonably have prevented it, which gives them a direct financial reason to improve defences. Analysts say the most effective systems combine speed with explanation, telling the customer plainly why a payment looks risky instead of simply blocking it without context. Customers are advised to help the system by keeping contact details current, answering verification calls promptly, and reporting suspicious messages so the bank can warn others. Regulators, meanwhile, are pressing telecoms firms and online platforms to do more to stop scam messages reaching people in the first place. The fight against fraud, banks concede, is now a shared effort between institutions, technology firms and the public, and it will not be won by any one of them alone. Reporting and analysis from sources such as World Bank track the same developments, and specialists following expanded fraud monitoring say the direction is now consistent across independent lines of evidence.
The Wider Context
For households and small firms, expanded fraud monitoring matters through prices and access rather than through market commentary. Changes at this level arrive as a rate on an offer letter, a fee on a statement or a product that quietly disappears from a comparison table. Consumer groups argue that transparency at exactly that point of decision is worth more than any amount of market-level reporting.
What Happens Next
The outlook for expanded fraud monitoring hinges on policy choices that will be made in the open over the coming quarters. Market participants are positioned for more than one outcome, which is why the immediate reaction to each announcement has been smaller than the commentary around it. For ordinary savers and borrowers, the advice from every quarter is the same: review your own position, not the headlines. You can follow related developments in our coverage of finance.
It is also worth remembering how quickly the picture in this area has changed before. Positions that looked settled a few years ago have been revised as new data arrived, and the same humility is appropriate now. The strongest coverage of this subject, and the most useful advice, tends to come from sources that update their views openly when the facts move, rather than defending an earlier position long after it has stopped fitting the evidence available.
